Argentina Expansion Playbook: Market Entry, Company Formation, and Compliance

Argentina combines one of Latin America’s largest domestic markets with one of its deepest, most cost-competitive technology and professional-services talent pools — Buenos Aires in particular has become a major nearshoring hub for software development, business process outsourcing, and remote professional services. That talent advantage is a genuine reason companies expand into Argentina even when currency and regulatory conditions call for extra planning.

Entering Argentina rewards the same discipline that applies everywhere in the region, with a bit more emphasis on getting the entity structure and payroll model right from the start, given how much local labor agreements shape compensation. Here is a practical Argentina market entry guide.

1) Market Overview

Argentina is one of the largest economies in Latin America by population and GDP, with a diversified base spanning agribusiness, energy, financial services, and — increasingly — technology and knowledge-based services. Buenos Aires is the commercial and financial center, and its concentration of English-speaking, technically skilled talent has made Argentina one of the region’s most established nearshoring and outsourcing destinations for U.S. and European companies.

Argentina’s economic environment has historically included more currency and regulatory volatility than some of its neighbors, including periods of exchange controls affecting the movement of funds in and out of the country. That’s a real planning variable, not a reason to avoid the market — but it does mean company formation and treasury setup in Argentina benefit from local expertise more than in a market with a longer track record of stability.

2) Entity Setup

Company formation in Argentina typically means incorporating a Sociedad Anónima (S.A.) or a Sociedad de Responsabilidad Limitada (S.R.L.), registering with the IGJ (Inspección General de Justicia) in Buenos Aires or the equivalent provincial registry elsewhere, and securing a CUIT tax ID from AFIP (Argentina’s federal tax authority) before the entity can legally invoice or hire. Business registration in Argentina runs through these two bodies, and the S.R.L. structure is often preferred by smaller foreign-owned subsidiaries for its simpler governance requirements relative to an S.A.

Companies not ready to incorporate can hire through an employer of record (EOR) in Argentina instead, which becomes the legal employer of local staff without requiring entity formation first — a common way to access Argentina’s talent pool while evaluating a longer-term local presence.

3) Compliance Basics

Payroll services in Argentina need to account for the SAC (sueldo anual complementario, commonly called aguinaldo), a mandatory bonus paid in two installments each June and December, plus contributions to ANSES, Argentina’s social security administration. Compensation and benefits are also shaped heavily by convenios colectivos — collective bargaining agreements that vary by industry and province and often set minimum pay scales above the statutory floor, which makes HR outsourcing in Argentina particularly valuable for companies unfamiliar with the relevant agreement for their sector.

Tax compliance in Argentina is layered across three levels: AFIP at the federal level, Ingresos Brutos (a provincial gross-receipts tax) at the provincial level, and additional municipal taxes depending on where the entity operates — a structure that trips up companies expecting a single national filing calendar. Corporate secretarial services in Argentina cover IGJ or provincial registry filings and the annual corporate updates required to stay in good standing, while accounting services in Argentina cover statutory bookkeeping and the federal, provincial, and municipal filings above.

4) Why Expand to Argentina

Argentina’s talent pool is the primary draw: a large base of skilled, cost-competitive professionals in technology and business services, concentrated in a handful of time zones convenient for U.S. and European companies. Paired with a sizable domestic consumer market, Argentina is worth the extra planning it requires — particularly around entity structure, payroll benchmarking against sector-specific labor agreements, and treasury setup — for companies whose expansion is talent-driven as much as market-driven.

Corpiya Can Help You Succeed

Corpiya supports companies expanding into Argentina across company formation, payroll and EOR, and accounting and tax compliance. For the full breakdown of services and country-specific requirements, see our complete guide to expanding your business to Argentina. This guide is part of Corpiya’s broader International Business Expansion Guide — see the full framework for choosing a market and entry model.

If you’re ready to enter the Argentine market with confidence, reach out to Corpiya at contact@corpiya.com or fill out the form below to start building your roadmap for success.

Disclaimer: This article is provided for general informational purposes only and does not constitute legal advice. Sebastien Gaddini is licensed to practice law in New York; this piece addresses business-expansion and compliance topics in a non-legal, informational capacity and should not be relied upon as legal counsel. For advice specific to your situation, consult a qualified attorney licensed in the relevant jurisdiction.
Put These Insights Into Action

Talk to our team about how this applies to your operations — wherever your business takes you, Corpiya is ready to support your next move.

Get In Touch

Contact - Send us a message

Related Insights

Back to All Insights

Peru Expansion Playbook: Market Entry, Company Formation, and Compliance

Peru is one of the Pacific Alliance’s most consistent economic performers, with a resource-rich export base, a growing services sector, and a regulatory environment that has matured quickly — Peru now has UBO disclosure rules, a digital services VAT, and one of the first comprehensive AI governance frameworks in Latin America. For companies used to treating Peru as an afterthought behind Mexico, Brazil, and Colombia, that combination of trade access and regulatory sophistication is worth a second look.

Expanding into Peru requires the same discipline as any Latin American market: validate demand, choose an entry model, form the right entity, and build compliance into operations from day one — not bolt it on after a filing deadline is missed. Here is a practical Peru market entry guide.

1) Market Overview

Peru is a member of the Pacific Alliance alongside Mexico, Colombia, and Chile, giving companies that establish a Peruvian entity preferential access to a trade bloc built specifically to reduce friction between its members. The economy is anchored by mining and natural resource exports, but services, agribusiness, and technology have grown steadily as a share of GDP, and Lima remains the commercial and financial center for most foreign entrants.

Peru’s regulatory environment has also become noticeably more sophisticated in the past two years. SUNAT (Peru’s tax authority) now requires Ultimate Beneficial Ownership affidavits from nearly all Peru-domiciled entities, extended VAT to digital services provided by non-resident companies, and Peru adopted one of Latin America’s first comprehensive AI governance frameworks. None of this makes Peru harder to enter than its regional peers — it means due diligence has to account for a few Peru-specific obligations that a generic Latin America playbook won’t flag.

2) Entity Setup

Company formation in Peru typically means incorporating a Sociedad Anónima Cerrada (S.A.C.) — the standard structure for a foreign-owned subsidiary — registering it with SUNARP (Peru’s public registry), and securing a RUC tax ID from SUNAT before the entity can legally invoice or hire. Business registration in Peru runs through these two bodies in sequence: SUNARP for the entity itself, then SUNAT for tax registration, with the exact documentation and timeline depending on whether directors and shareholders are based in Peru or abroad.

Companies not ready to commit to a Peruvian entity can hire through an employer of record (EOR) in Peru instead, which becomes the legal employer of local staff without requiring incorporation first — a common first step before committing to full company formation.

3) Compliance Basics

Once a Peruvian entity is live, payroll services in Peru need to account for gratificaciones (statutory bonuses paid in July and December), CTS (Compensación por Tiempo de Servicios, a severance-savings deposit made twice a year), and contributions to either the public ONP pension system or a private AFP. HR outsourcing in Peru typically covers this payroll cycle plus compliance with Peru’s labor inspectorate, SUNAFIL.

Tax compliance in Peru centers on SUNAT filings, and foreign providers of digital services specifically need to understand Peru’s newer VAT rules — see our breakdown of Peru’s digital services VAT for what registration and monthly reporting actually require. Nearly every Peru-domiciled entity also now falls under phased UBO disclosure deadlines; our Peru UBO affidavit update covers the current filing windows and penalties for missing them. And any company deploying AI tools as part of its Peru operations should be aware of Peru’s AI governance framework, covered in our analysis of Peru’s AI regulation — it’s a compliance area most companies don’t expect to encounter this early in a market entry.

Corporate secretarial services in Peru cover SUNARP filings, board and shareholder record-keeping, and the annual updates that keep an entity in good standing once it’s formed. Accounting services in Peru cover statutory bookkeeping and the SUNAT-linked filings above.

4) Why Expand to Peru

Peru offers a combination that’s genuinely uncommon in the region: Pacific Alliance trade access, a resource-driven export economy that has weathered global volatility reasonably well, and a regulatory environment that — while it now requires more diligence than it did five years ago — is maturing in ways that make Peru a more credible long-term base rather than a less attractive one. Companies already operating in Mexico, Colombia, or Chile often find Peru’s entity and compliance requirements familiar rather than novel, which lowers the effective cost of adding it as a fourth market.

Corpiya Can Help You Succeed

Corpiya supports companies expanding into Peru across company formation, payroll and EOR, and accounting and tax compliance — including the UBO, digital VAT, and AI governance obligations covered above. For the full breakdown of services and country-specific requirements, see our complete guide to expanding your business to Peru. This guide is part of Corpiya’s broader International Business Expansion Guide — see the full framework for choosing a market and entry model.

If you’re ready to enter the Peruvian market with confidence, reach out to Corpiya at contact@corpiya.com or fill out the form below to start building your roadmap for success.

Disclaimer: This article is provided for general informational purposes only and does not constitute legal advice. Sebastien Gaddini is licensed to practice law in New York; this piece addresses business-expansion and compliance topics in a non-legal, informational capacity and should not be relied upon as legal counsel. For advice specific to your situation, consult a qualified attorney licensed in the relevant jurisdiction.

Put These Insights Into Action

Talk to our team about how this applies to your operations — wherever your business takes you, Corpiya is ready to support your next move.

Get In Touch

Contact - Send us a message

Related Insights

Back to All Insights

Subsidiary vs. Branch Office: Which Structure Fits Your Expansion?

Quick answer: A subsidiary is a separate legal entity incorporated in the local jurisdiction, wholly or partly owned by the parent company, which shields the parent from the subsidiary’s liabilities. A branch office is an extension of the parent company itself — not a separate legal entity — meaning the parent is directly liable for everything the branch does. Choose a subsidiary when you want liability protection, local credibility, or a long-term independent presence; choose a branch office when you want a faster, lower-cost way to establish a taxable local presence without creating an entirely separate company.

Once a company has decided to expand into a new market and settled on forming a local presence rather than working through a distributor or an Employer of Record, the next decision is what kind of legal presence to form. The two most common options — a subsidiary or a branch office — solve the same basic problem (a recognized local presence) with very different implications for liability, taxation, and long-term flexibility. This is part of the broader entity and compliance structure decision every international expansion requires.

What Is a Subsidiary?

A subsidiary is a distinct legal entity formed under local law, owned in whole or in part by the parent company. Because it’s legally separate, the subsidiary is responsible for its own debts, contracts, and liabilities — the parent company’s exposure is generally limited to its investment in the subsidiary. Subsidiaries file their own local tax returns, can enter into contracts in their own name, and typically carry more credibility with local customers, partners, and regulators than a branch.

The tradeoff is setup complexity: forming a subsidiary usually requires registration, minimum capital, appointed local directors or representatives, and ongoing corporate governance and compliance obligations separate from the parent company’s own.

What Is a Branch Office?

A branch office is not a separate legal entity — it’s a registered extension of the parent company operating in a foreign jurisdiction. Because there’s no legal separation, the parent company is directly liable for the branch’s contracts, debts, and legal obligations. Branch offices are often faster and cheaper to register than a subsidiary, since there’s no new entity to incorporate, but that speed comes with the parent absorbing the branch’s liability directly.

Some jurisdictions also tax and regulate branches differently than subsidiaries — in some cases more strictly, specifically because branches don’t carry the same local capitalization and governance requirements a subsidiary does.

FactorSubsidiaryBranch Office
Legal identitySeparate legal entityExtension of the parent company
LiabilityLimited to the subsidiary itselfParent company directly liable
Setup time & costHigher — incorporation, capital, governanceGenerally lower and faster
Local contractingContracts in its own nameContracts often still tied to the parent
Local credibilityTypically higher with customers and regulatorsCan appear less established locally
Ongoing complianceSeparate filings, governance, auditsSimpler, but tied to parent’s obligations
Best forLong-term, independent local presenceFaster, lower-commitment market entry

How to Decide: A Practical Framework

1. How much liability protection do you need?

If the local operation carries meaningful commercial risk — contracts, employees, customer-facing liability — a subsidiary’s separate legal status protects the parent company’s broader assets. A branch office offers no such shield; every obligation flows back to the parent.

2. Is this a long-term commitment or a way to test the market?

A subsidiary makes more sense as a long-term, independent local presence, since the up-front setup cost is amortized over time. A branch office can be a reasonable way to establish a taxable presence faster while a company is still validating demand, with the option to convert to a subsidiary later.

3. What do local tax and regulatory rules require or reward?

Tax treatment, minimum capital rules, and sector-specific licensing requirements vary meaningfully by country and sometimes favor one structure over the other for reasons that have nothing to do with liability. This is exactly the kind of jurisdiction-specific detail worth confirming with local counsel and company-formation support before committing to a structure.

A Common Misconception Worth Correcting

Many companies assume a branch office is automatically the “lighter,” cheaper option and a subsidiary is automatically the “heavier,” more expensive one. That’s not always true. Some jurisdictions impose stricter tax treatment or reporting requirements on branches specifically because they lack a subsidiary’s local capitalization and governance structure — in those cases, the branch can end up costing more over time despite the lower setup cost. And because a branch carries no separate liability shield, the “lighter” option can also be the riskier one. The right structure depends on the specific jurisdiction and the nature of the local operation, not a general rule of thumb.

How Corpiya Supports Entity Formation

Corpiya helps companies register the right entity type for the jurisdiction, capital structure, and long-term plans behind the expansion — and keeps it compliant once it’s live. See Company Formation services, or start with the broader International Business Expansion Guide for the full framework this decision fits into.

More Subsidiary vs. Branch Office Questions, Answered

Which is faster to set up, a subsidiary or a branch office?

A branch office is generally faster to register since there’s no new legal entity to incorporate — it’s an extension of the parent company’s existing registration. A subsidiary requires full incorporation, which typically takes longer and involves more documentation.

Does a branch office pay taxes locally?

Yes — a branch office typically creates a taxable presence in the local jurisdiction and is subject to local tax on the income it generates there, even though it isn’t a separate legal entity. Tax treatment specifics vary by country and sometimes differ meaningfully from how a subsidiary is taxed.

Can a branch office sign local contracts?

A branch office can typically enter into contracts locally, but because it isn’t a separate legal entity, those obligations ultimately belong to the parent company rather than being contained within the branch.

Is a subsidiary always better for liability protection?

For liability protection specifically, yes — a subsidiary’s separate legal status is what shields the parent company from its debts and obligations, which a branch office cannot offer. Whether that protection is worth the added setup and compliance cost depends on the risk profile of the local operation.

What happens if I want to close a branch office versus a subsidiary?

Winding down a branch office is generally simpler since there’s no separate entity to formally dissolve — though notice and deregistration requirements still apply. Closing a subsidiary typically involves a more formal dissolution and liquidation process under local corporate law.

Disclaimer: This article is provided for general informational purposes only and does not constitute legal advice. Sebastien Gaddini is licensed to practice law in New York; this piece addresses business-expansion and compliance topics in a non-legal, informational capacity and should not be relied upon as legal counsel. For advice specific to your situation, consult a qualified attorney licensed in the relevant jurisdiction.

Put These Insights Into Action

Talk to our team about how this applies to your operations — wherever your business takes you, Corpiya is ready to support your next move.

Get In Touch

Contact - Send us a message

Related Insights

Back to All Insights

EOR vs. Local Subsidiary for International Expansion

Quick answer: An Employer of Record (EOR) lets you hire employees in a new country immediately without forming any legal entity — the EOR becomes the legal employer and absorbs compliance risk, so you can be operating in days to weeks. A local subsidiary is your own legal entity in that country, giving you full operational and tax control but requiring registration, capital, and ongoing compliance obligations that typically take weeks to months to complete. Choose an EOR to test a market or hire a small team quickly; choose a subsidiary once you have sustained operations, local contracting needs, or enough headcount that entity overhead pays for itself.

This is the make-or-buy decision behind almost every international expansion: build your own legal presence, or rent one through an intermediary that already has it. It’s a broader question than the PEO vs. EOR decision, which assumes you’re choosing between two ways to employ people once an entity may or may not already exist. Here, the question is whether to form that entity at all.

What Is an Employer of Record (EOR)?

An EOR is a third-party organization that becomes the legal employer of your staff in a country where you have no registered entity. It issues the local employment contract, runs payroll, remits statutory withholdings, and carries the legal liability for labor-law compliance — while you retain full control over the employee’s actual work, targets, and reporting line. Because no entity formation is required, an EOR typically lets you make a hire within days to a few weeks.

What Is a Local Subsidiary?

A local subsidiary is your own legal entity, incorporated under the laws of the target country. As the subsidiary’s legal employer, you have full control over employment terms, can sign contracts and hold assets locally in the entity’s own name, and establish a permanent, credible local presence. The tradeoff is setup time and ongoing obligations: entity registration, minimum capital in some jurisdictions, local directors or representation, and continuous corporate governance and compliance once the entity is live.

FactorEORLocal Subsidiary
Entity required?NoYes
Time to operateDays to a few weeksWeeks to months
Legal employerThe EORYou (the parent company)
Local contractingLimited — typically routed through the EORFull — contracts in the entity’s own name
Compliance liabilityHeld by the EORHeld by you
Cost structurePer-employee fee, no entity overheadEntity formation and maintenance costs + payroll
Best forTesting a market, small teams, fast entrySustained operations, local contracting, larger teams

How to Decide: A Practical Framework

1. How many people are you hiring, and how fast do you need them working?

For a first hire or a small team, an EOR is almost always the faster and cheaper path — the cost of forming and maintaining an entity for one or two employees rarely pencils out. As headcount grows, the per-employee EOR fee eventually crosses over with the fixed cost of running your own entity.

2. Do you need to contract locally, hold local IP, or invoice in-country?

An EOR is built around employment specifically — it doesn’t give you a local legal entity that can sign commercial contracts, hold intellectual property, or invoice customers directly in that jurisdiction. If your expansion needs local contracting capability beyond hiring staff, a subsidiary is usually necessary regardless of headcount.

3. What’s your time horizon in this market?

An EOR is a reasonable long-term solution for a small, ongoing footprint — not just a temporary bridge. But for a company committing to sustained, independent operations in a market, the up-front cost of a subsidiary is typically worth it for the local credibility, contracting flexibility, and control it provides.

A Common Misconception Worth Correcting

It’s easy to assume there’s a hard employee-count ceiling past which you’re required to switch from an EOR to a subsidiary. There isn’t one. The real constraint is a cost-efficiency crossover point, not a fixed rule — some companies run an EOR indefinitely for a small satellite team precisely because forming an entity for a handful of people never becomes worth it, regardless of how long the relationship lasts. Others form a subsidiary early, even with a small initial headcount, because they need local contracting capability or strategic tax structuring that an EOR simply can’t provide.

How Corpiya Supports This Decision

Corpiya supports both sides of this decision: Global HR & EOR services to hire quickly without forming an entity, and Company Formation once a subsidiary makes more sense. For the entity-type decision that follows — once you’ve decided to form one — see Subsidiary vs. Branch Office, or start with the full International Business Expansion Guide.

More EOR vs. Local Subsidiary Questions, Answered

EOR vs local subsidiary: which should I use to expand into a new country?

Use an EOR when you’re testing a market or hiring a small team quickly, since it requires no entity formation and gets you operating in days to weeks. Use a local subsidiary once you have sustained operations, need to contract locally, or have enough headcount that entity overhead pays for itself.

Is an EOR cheaper than forming a subsidiary?

For a small number of employees, yes — EOR fees are charged per employee with no entity overhead, while a subsidiary requires ongoing formation and maintenance costs regardless of headcount. The cost comparison shifts as headcount grows and the fixed cost of running an entity gets spread across more employees.

Can I switch from an EOR to a local subsidiary later?

Yes — this is a common growth path. Companies often start with an EOR to make their first hires in a market, then form a subsidiary once headcount and revenue justify it, transitioning existing employees to direct employment under the new entity.

Does an EOR let me sign contracts or invoice customers locally?

No — an EOR is an employment solution, not a general-purpose local entity. It doesn’t give you the ability to contract, hold IP, or invoice in the entity’s own name locally. If you need that capability, a subsidiary is typically required.

How many employees before a local subsidiary makes more sense than an EOR?

There’s no fixed number — it depends on comparing the EOR’s per-employee fee against the fixed cost of forming and maintaining a subsidiary, plus whether you need local contracting capability the EOR can’t provide. Some companies stay on an EOR indefinitely for a small team; others form a subsidiary early for strategic reasons unrelated to headcount.

Disclaimer: This article is provided for general informational purposes only and does not constitute legal advice. Sebastien Gaddini is licensed to practice law in New York; this piece addresses business-expansion and compliance topics in a non-legal, informational capacity and should not be relied upon as legal counsel. For advice specific to your situation, consult a qualified attorney licensed in the relevant jurisdiction.

Put These Insights Into Action

Talk to our team about how this applies to your operations — wherever your business takes you, Corpiya is ready to support your next move.

Get In Touch

Contact - Send us a message

Related Insights

Back to All Insights

Ecuador Expansion Playbook: Market Entry, Company Formation, and Compliance

Ecuador is one of the more overlooked markets in Latin America for foreign expansion, in part because it doesn’t carry the market size of Brazil or Mexico — but it offers something neither of those markets does: a fully dollarized economy. Every price, payroll run, and contract in Ecuador is denominated in U.S. dollars, which removes an entire category of currency risk that shapes how companies plan an entry into almost every other market in the region.

That doesn’t make Ecuador simpler to enter than its neighbors — entity formation, labor compliance, and tax registration still require the same discipline any Latin American market does. Here is a practical Ecuador market entry guide.

1) Market Overview

Ecuador has used the U.S. dollar as its official currency since 2000, which removes exchange-rate volatility as a planning variable — a meaningful simplification for companies that have found currency risk to be one of the harder parts of budgeting for expansion elsewhere in Latin America. The economy is built on oil, agricultural exports (bananas, shrimp, cacao, and cut flowers are major categories), and a growing services sector, with Quito and Guayaquil serving as the country’s two primary commercial hubs.

Ecuador is also a member of the Andean Community, giving companies that establish an Ecuadorian entity a regional trade relationship with Colombia, Peru, and Bolivia. The regulatory environment is more straightforward than some of its neighbors’, though foreign investors still need to work through Ecuador’s company registry and tax authority in the correct sequence to operate legally.

2) Entity Setup

Company formation in Ecuador typically means incorporating a Sociedad Anónima or a Compañía Limitada, registering with the Superintendencia de Compañías (Ecuador’s corporate registry), and securing a RUC tax ID from the SRI (Servicio de Rentas Internas) before the entity can legally invoice or hire. Business registration in Ecuador runs through these two bodies, with the Compañía Limitada generally preferred by smaller foreign-owned subsidiaries and the Sociedad Anónima more common for larger operations or those anticipating outside investment.

Companies not ready to incorporate can hire through an employer of record (EOR) in Ecuador instead, which becomes the legal employer of local staff without requiring entity formation first — useful for testing the market or making a first hire before committing further.

3) Compliance Basics

Payroll services in Ecuador need to account for two statutory bonuses: décimo tercer sueldo (a 13th-month payment made in December) and décimo cuarto sueldo (a 14th-month payment tied to the school calendar, paid in different months depending on the region), plus mandatory contributions to the IESS, Ecuador’s social security institute. HR outsourcing in Ecuador typically covers this payroll cycle along with onboarding and compliance tracked against Ministerio del Trabajo requirements.

Tax compliance in Ecuador centers on SRI registration, monthly VAT and withholding filings, and income tax returns, while corporate secretarial services in Ecuador cover the annual filings and reporting the Superintendencia de Compañías requires to keep an entity in good standing. Accounting services in Ecuador cover statutory bookkeeping and the SRI-linked filings above — and because Ecuador’s currency is the U.S. dollar, financial reporting for a U.S. parent company involves one less layer of currency translation than most other markets in the region.

4) Why Expand to Ecuador

Ecuador’s dollarization is the standout reason companies add it to a Latin American footprint: it removes currency risk from pricing, payroll, and repatriation decisions in a way no other market in the region can offer. Combined with Andean Community trade access and a natural-resource and agricultural export base that has proven durable, Ecuador is a reasonable next step for companies already operating in Colombia or Peru that want a third Andean market without adding currency exposure to the mix.

Corpiya Can Help You Succeed

Corpiya supports companies expanding into Ecuador across company formation, payroll and EOR, and accounting and tax compliance. For the full breakdown of services and country-specific requirements, see our complete guide to expanding your business to Ecuador. This guide is part of Corpiya’s broader International Business Expansion Guide — see the full framework for choosing a market and entry model.

If you’re ready to enter the Ecuadorian market with confidence, reach out to Corpiya at contact@corpiya.com or fill out the form below to start building your roadmap for success.

Disclaimer: This article is provided for general informational purposes only and does not constitute legal advice. Sebastien Gaddini is licensed to practice law in New York; this piece addresses business-expansion and compliance topics in a non-legal, informational capacity and should not be relied upon as legal counsel. For advice specific to your situation, consult a qualified attorney licensed in the relevant jurisdiction.

Put These Insights Into Action

Talk to our team about how this applies to your operations — wherever your business takes you, Corpiya is ready to support your next move.

Get In Touch

Contact - Send us a message

Related Insights

Back to All Insights

Mexico’s 2026 Labor Reform & Outsourcing Enforcement: What Multinational Employers Must Do Now

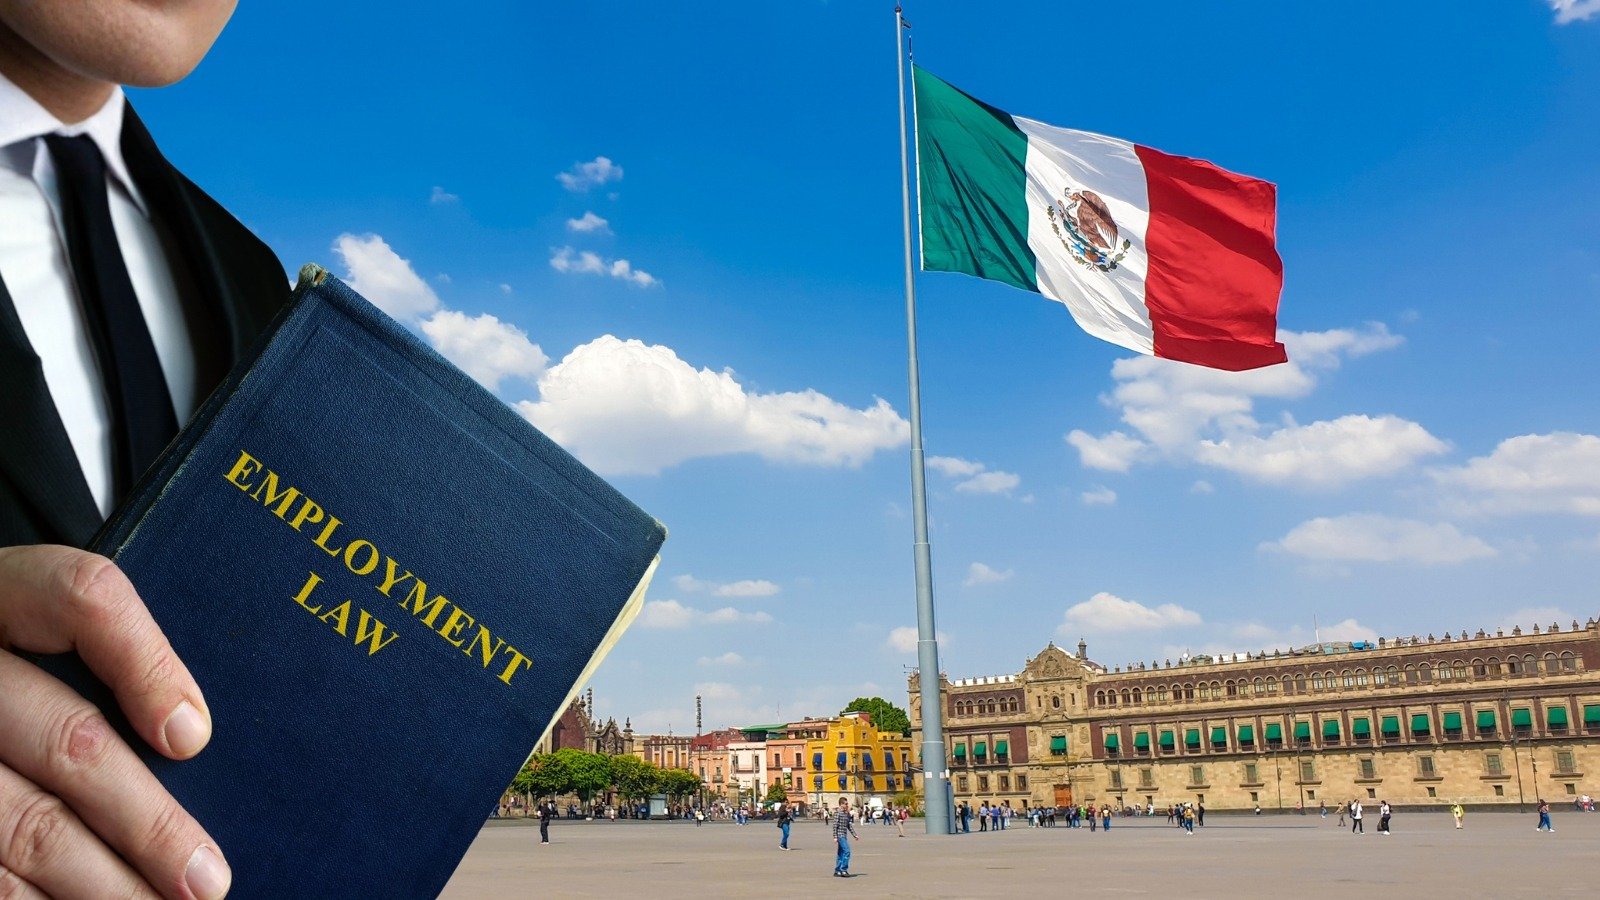
Employment law book with Mexican flag - Mexico 2026 labor reform

Mexico’s labor enforcement environment changed in 2026 — not in policy, but in practice. Authorities are now actively inspecting, cross-referencing registries, and holding multinational employers accountable for documentation gaps they assumed no one would check.

If your organization operates in Mexico, the question is no longer whether enforcement is coming — it’s whether you’ll be ready when it does.

What Mexico’s 2026 Labor Reform Actually Requires

Mexico’s labor compliance framework has been evolving since the landmark 2021 subcontracting reform, which eliminated most forms of personnel outsourcing and created strict rules for specialized service arrangements. In 2026, enforcement has shifted from legislative transition to active inspection.

The Secretaría del Trabajo y Previsión Social (STPS) and the Instituto Mexicano del Seguro Social (IMSS) are now operating under reinforced inspection mandates. Authorities are targeting the following compliance areas simultaneously:

  • Outsourcing and subcontracting structures govern how employers engage workers through third parties. Under the 2021 reform, only companies registered in the REPSE — the Registro de Prestadoras de Servicios Especializados o de Obras Especializadas — may legally provide specialized labor services to another company. Inspectors are now actively verifying whether employers are contracting only with valid, current REPSE registrants.

  • Payroll controls and social security contributions are under heightened scrutiny. IMSS and INFONAVIT filings must align with actual payroll records. Discrepancies — even administrative ones — are generating formal observations and fines.

  • Training and skill certification obligations require employers to maintain documented, current training programs for all employees. This is a statutory requirement under the Federal Labor Law (Ley Federal del Trabajo), and inspectors are requesting records on-site.

  • Workplace safety and occupational health compliance is being verified through unannounced STPS inspections. Safety protocols, incident reporting records, and hazard identification documents must be organized and immediately accessible.

  • The 40-hour workweek transition is advancing through Mexico’s legislative process following a constitutional amendment reducing the maximum workweek from 48 to 40 hours. Employers who have not yet modeled the payroll, scheduling, and overtime impact of this change are behind.

Why This Is an Organizational Problem, Not Just a Legal One

Most labor compliance failures in Mexico do not stem from a company intentionally ignoring the law. They stem from fragmented internal structures that make compliance invisible — or impossible to demonstrate on short notice.

The enforcement gap is operational. HR teams track headcount. Payroll teams manage contributions. Legal teams review contracts. But when an inspector arrives and requests a unified compliance picture, no single team can produce it.

For multinational employers, this fragmentation is amplified. Headquarters may have no real-time visibility into whether a Mexico-based provider’s REPSE registration is current, whether training certifications are on file, or whether payroll records are reconciled with social security filings. The Mexico team assumes it is covered. Headquarters assumes the Mexico team is handling it. The audit reveals neither assumption was being verified.

Centralized entity management and compliance infrastructure — not more legal opinions — is what closes this gap.

The 7 Compliance Pressure Points for Mexico Operations in 2026

Employers with operations or teams in Mexico should treat the following as immediate review priorities:

  1. REPSE registry status of all specialized service providers. Confirm that every third-party provider engaged for specialized services holds a valid, non-expired REPSE registration. This must be checked at contract initiation and at each renewal cycle — not just once.

  2. Payroll-to-IMSS reconciliation. Verify that payroll records and IMSS contribution filings are fully aligned. Any gap between reported salaries and actual contributions creates both a fine exposure and a worker benefit liability.

  3. INFONAVIT contribution accuracy. INFONAVIT contributions must be calculated and filed correctly for all eligible employees. Errors here compound over time and are rarely self-correcting.

  4. Training program documentation. Confirm that mandatory training obligations under Articles 153-A through 153-X of the Federal Labor Law are being met and that employee-level completion records are maintained in an accessible format.

  5. Workplace safety compliance file. Verify that a current STPS safety compliance file exists, including hazard identification, safety protocols, incident history, and emergency procedures. This file must be production-ready for inspection — not reconstructed after a notice arrives.

  6. Profit-sharing (PTU) calculation accuracy. The 2021 reform introduced a cap and floor structure for profit-sharing obligations under outsourcing arrangements. Confirm your PTU calculations reflect current rules and that subcontracting arrangements properly allocate this liability.

  7. 40-hour workweek impact modeling. Begin modeling the operational and payroll cost impact of the workweek reduction now. Companies that wait for final implementing regulations to act will face compressed timelines and higher transition costs.

What Regulators Are Expecting from Multinational Employers

Mexican labor authorities are not treating multinational employers as uninformed newcomers. Inspectors are applying the same evidentiary standards to a global company’s Mexico subsidiary as they would to a domestic employer — and in some cases, holding parent companies and contracting entities to joint liability standards.

Regulators are specifically looking for the following from companies with cross-border workforce structures:

  • Documentary coherence. Records must tell a consistent story. Payroll, contracts, training logs, and social security filings must align with each other and with the actual workforce structure on the ground.

  • Structural transparency. The relationship between the employer of record, the contracting company, and the specialized service provider must be clearly documented and defensible as a lawful arrangement under the 2021 subcontracting rules.

  • Ongoing compliance, not point-in-time compliance. Registrations, certifications, and filings are expected to be current — not as of the last audit, but as of today.

  • Designated accountability. Inspectors expect to identify a responsible party within the organization who owns labor compliance. Companies that cannot produce this accountability demonstrate systemic risk.

Frequently Asked Questions: Mexico Labor Compliance 2026

What is REPSE and why does it matter for my company in Mexico?
REPSE is Mexico’s federal registry for companies that provide specialized labor or services to other businesses. Under the 2021 reform, it is illegal for a company to contract specialized workers through a provider that is not registered in REPSE. If your company engages any outsourced specialized service provider in Mexico, that provider must hold a valid, current REPSE registration — and you are responsible for verifying it. Contracting with an unregistered provider exposes your company to joint liability and administrative fines.

What are the penalties for non-compliance with Mexico’s labor outsourcing rules? Penalties include administrative fines, back-payment of social security contributions, INFONAVIT liabilities, PTU recalculations, and in cases of repeated or deliberate violations, criminal liability under the Federal Tax Code for improper deductions linked to non-compliant outsourcing arrangements. Joint and several liability means the contracting company — not just the service provider — can be held directly responsible.

How does the 40-hour workweek reform affect payroll and overtime calculations? Mexico’s constitutional amendment reduces the maximum legal workweek from 48 to 40 hours. Once fully implemented through secondary legislation, any hours worked beyond 40 in a week will qualify as overtime, subject to premium pay under the Federal Labor Law. For employers currently operating on 48-hour schedules, this represents a structural payroll cost increase unless scheduling is restructured. The transition timeline is still being defined, but the amendment is constitutional — implementation is a matter of when, not if.

What documentation does a company need to survive a Mexico labor inspection? At minimum, inspectors will request: current employment contracts for all workers, IMSS and INFONAVIT contribution records, payroll receipts (recibos de nómina) for the prior 12 months, REPSE certificates for all specialized service providers, training program records and employee-level certifications, a current workplace safety file, and documentation of PTU calculations and payments. Companies that cannot produce these records quickly and in organized form are treated as non-compliant regardless of actual practice.

Can a U.S.-based parent company be held liable for Mexico labor violations by its subsidiary or service provider?
In practice, joint and several liability provisions in Mexico’s labor reform mean that contracting parties — including foreign parent companies or U.S.-based entities that directly engage Mexican service providers — can be held liable for compliance failures down the chain. This is particularly relevant for nearshore arrangements where the U.S. entity is the contracting party. Legal exposure is not limited to the Mexico-based legal entity.

What is the difference between outsourcing and specialized services under Mexico’s 2021 reform?
The 2021 reform effectively banned traditional personnel outsourcing — where a staffing company supplies workers who perform the core business activities of the client. What is permitted is specialized services: arrangements where a provider delivers services or executes work that is not part of the client company’s primary corporate purpose. The provider must be REPSE-registered, and the arrangement must be documented with a formal service agreement specifying the scope of specialized work.

The Compliance Infrastructure Imperative

Mexico’s 2026 enforcement acceleration is a stress test for how multinational employers have structured their compliance operations. Companies that built centralized, documented, and verifiable compliance systems after the 2021 reform are positioned to pass that test. Companies that managed compliance informally — through local relationships, tribal knowledge, or periodic legal reviews — are the ones now facing audit exposure.

The underlying lesson is not specific to Mexico. Every jurisdiction in Latin America is moving toward greater formalization, registry-based enforcement, and documentary accountability. The employers who build compliance infrastructure today are the ones who will operate without disruption across the region for the next decade.

Work With Corpiya Business Services

Corpiya Advisory Services supports multinational employers across Latin America and internationally with the compliance infrastructure, entity management, and operational systems needed to stay ahead of enforcement environments like Mexico’s. From REPSE monitoring and payroll alignment to centralized entity management through our proprietary HoneyBee EMS platform, we provide the structural support that transforms compliance from a recurring risk into a managed function.

If your organization has employees, contractors, or service providers in Mexico — or is building a nearshore presence in the region — now is the right time to review your compliance posture.

📩 contact@corpiya.com 🌐 www.corpiya.com

Disclaimer: This article is provided for general informational purposes only and does not constitute legal advice. Sebastien Gaddini is licensed to practice law in New York; this piece addresses business-expansion and compliance topics in a non-legal, informational capacity and should not be relied upon as legal counsel. For advice specific to your situation, consult a qualified attorney licensed in the relevant jurisdiction.

Put These Insights Into Action

Talk to our team about how this applies to your operations — wherever your business takes you, Corpiya is ready to support your next move.

Get In Touch

Contact - Send us a message

Related Insights

Back to All Insights

Brazil’s 2026 Tax Reform: What Multinational Companies Must Do Now

Brazil's 2026 Tax Reform: What Multinational Companies Must Do Now

Brazil’s Tax Reform Is Exposing a Hidden Problem in Multinational Companies.
And it has nothing to do with tax calculation.
Brazil’s most significant tax overhaul in decades is no longer on the horizon — it is actively underway. The dual VAT reform replacing multiple legacy indirect taxes with two new frameworks, the Contribuição sobre Bens e Serviços (CBS) and the Imposto sobre Bens e Serviços (IBS), entered its implementation phase in 2026 and will run through a transition period ending in 2033.

For multinational corporations with operations, subsidiaries, or supply chain relationships in Brazil, the clock is no longer ticking. It has already started counting down.

But the most urgent challenge facing companies right now is not tax calculation. It is organizational visibility — knowing where compliance-critical information lives across legal, finance, payroll, and local country teams before regulators come asking for it.

What Is Brazil’s Dual VAT Reform (CBS + IBS)?

Brazil’s tax reform consolidates a historically fragmented indirect tax system — including PIS, COFINS, ICMS, ISS, and IPI — into a cleaner dual-VAT structure:

  • CBS (Contribuição sobre Bens e Serviços): A federal-level contribution replacing PIS and COFINS

  • IBS (Imposto sobre Bens e Serviços): A state and municipal-level tax replacing ICMS and ISS

The transition is phased between 2026 and 2033, with companies expected to operate under both legacy and new systems simultaneously during much of that window. Regulators are increasingly requiring centralized, auditable data trails across entities — not just accurate tax filings, but documented evidence of how compliance decisions were made and who was responsible for them.

Why This Reform Is Operationally Critical Right Now

The “Dual Running” Problem

During the transition period, businesses must maintain compliance under both the old and new tax frameworks simultaneously. This creates double the reporting obligations, double the risk of inconsistency, and double the demand on internal teams — most of whom were not built to manage this kind of parallel operation.

Fragmented Information Across Teams Is the Real Risk

Here is the hidden problem that Brazil’s reform is exposing: in most multinationals, compliance information is not centralized. Tax data lives in one system. Legal entity records live in another. Payroll obligations are managed locally. Finance reports upward through a separate structure entirely.

When Brazilian regulators request an auditable data trail — and they increasingly will — companies scramble. Not because the information does not exist, but because no one has a single, reliable view of it.

ERP and Invoicing Systems Are Not Ready

Many companies operating in Brazil are running ERP or invoicing configurations that predate this reform by a decade or more. The new CBS/IBS framework requires updated tax codes, new invoice fields, and different reporting formats. Legacy systems require significant remediation before they can produce compliant output under the new rules.

The 7 Operational Pressure Points of Brazil’s Tax Transition

Companies navigating this reform are finding pressure in the following areas. Use this as a readiness checklist:

  1. Multi-entity compliance coordination — Are all Brazilian subsidiaries and branches filing consistently under the transition rules?

  2. ERP and EMS integration — Have your enterprise systems been updated to support CBS/IBS tax codes and invoice formats?

  3. Invoicing system compliance — Are electronic invoices (NF-e, NFS-e) being generated correctly under the new framework?

  4. Treasury and accounting alignment — Has cash flow modeling been updated to reflect CBS/IBS timing and offset rules?

  5. Indirect tax mapping — Have all products and services been re-categorized under the new tax classification system?

  6. Corporate restructuring review — Does your current Brazil entity structure still make sense under the new tax regime?

  7. Entity-level reporting consistency — Can you produce a consistent, auditable compliance record across all Brazilian entities on demand?

If the answer to any of these is “not yet” or “we are not sure,” your organization is in a position that is increasingly common — and increasingly risky.

What Regulators Are Now Expecting From Multinationals

Brazilian tax authorities are not simply asking companies to file correctly. The direction of regulatory pressure in 2026 is toward:

  • Centralized and auditable entity data that can be produced quickly upon request

  • Demonstrated organizational readiness, not just point-in-time compliance

  • Cross-entity consistency, particularly for multinationals operating through multiple Brazilian legal entities

This shifts the compliance burden from a tax function problem to an enterprise-wide organizational problem. Finance, legal, operations, and local country teams all need to be working from the same information — and that information needs to be accessible, current, and verifiable.

Frequently Asked Questions: Brazil’s 2026 Tax Reform

  • What taxes are being replaced by Brazil’s CBS and IBS? The reform replaces PIS, COFINS, ICMS, ISS, and IPI with two new taxes: the federal CBS and the state/municipal IBS.

  • When does Brazil’s dual VAT transition end? The transition period runs from 2026 through 2033. Companies will operate under both old and new frameworks simultaneously during much of this period.

  • What is the biggest compliance risk for multinationals during the transition? Fragmented information across legal, finance, payroll, and local teams. Regulators expect centralized, auditable data trails — and most multinationals are not currently structured to produce them quickly.

  • Do ERP systems need to be updated for Brazil’s tax reform? Yes. Most legacy ERP and invoicing systems require updates to support new CBS/IBS tax codes, invoice fields, and reporting formats required under the new framework.

  • What should multinationals do now to prepare for Brazil’s tax reform? Conduct an entity-level compliance audit, assess ERP and invoicing system readiness, and establish a centralized view of compliance obligations across all Brazilian entities.

The Bottom Line: Brazil’s Reform Is an Organizational Readiness Test

Brazil’s dual VAT transition is one of the most impactful regulatory shifts affecting multinational corporations operating in Latin America today. The companies that will navigate it successfully are not necessarily those with the most sophisticated tax calculations — they are the ones with the clearest view of their own operations.

Centralized entity data. Aligned teams. Auditable records. These are the competitive advantages that will separate resilient multinationals from reactive ones between now and 2033.

How Corpiya Helps Multinationals Navigate Brazil’s Tax Transition

At Corpiya, we work with multinational corporations to bring clarity and control to exactly this kind of regulatory complexity. Our integrated approach combines Entity Management Solutions (EMS) with Corpiya Advisory Services — giving companies a unified view of compliance obligations, entity structures, and operational data across jurisdictions.

If your organization is facing fragmented information, ERP readiness gaps, or multi-entity coordination challenges ahead of Brazil’s CBS/IBS transition, we can help you build the infrastructure to meet it with confidence.

Get in touch with our team at contact@corpiya.com or visit www.corpiya.com to start the conversation.

Disclaimer: This article is provided for general informational purposes only and does not constitute legal advice. Sebastien Gaddini is licensed to practice law in New York; this piece addresses business-expansion and compliance topics in a non-legal, informational capacity and should not be relied upon as legal counsel. For advice specific to your situation, consult a qualified attorney licensed in the relevant jurisdiction.

Put These Insights Into Action

Talk to our team about how this applies to your operations — wherever your business takes you, Corpiya is ready to support your next move.

Get In Touch

Contact - Send us a message

Related Insights

Back to All Insights

United States: New UBO Requirements for New York LLCs

United States: New UBO Requirements for New York LLCs

Who Must File Under the New York LLC Transparency Act?

As of 2026, the New York LLC Transparency Act (NY LLCTA) primarily requires LLCs formed under the laws of a foreign country and authorized to do business in New York to file beneficial ownership information or an attestation of exemption. LLCs formed in New York or another U.S. state are currently exempt from the Act’s beneficial ownership reporting requirements.

New York Leads on LLC Transparency

New York’s Limited Liability Company Transparency Act (NY LLCTA) took effect on January 1, 2026, creating new beneficial ownership disclosure requirements for certain foreign LLCs operating in the state. The law requires covered entities to file beneficial ownership information or an attestation of exemption with the New York Department of State and to update or reaffirm that information annually.

Federal Context: Corporate Transparency Act Changes

The federal Corporate Transparency Act (CTA) originally established broad beneficial ownership reporting requirements for U.S. businesses. However, federal rules changed significantly in 2025. U.S.-formed entities are currently exempt from federal BOI reporting, while certain entities formed under foreign law and registered to do business in the United States remain subject to federal reporting requirements.

The New York LLC Transparency Act operates at the state level and should therefore be evaluated separately from federal CTA requirements. Companies with cross-border or multi-state structures should determine which federal and state reporting obligations apply to each entity.

New York LLCTA Key Requirements

Filing Requirements

Covered entities must submit either a beneficial ownership disclosure statement or an attestation of exemption to the New York Department of State, depending on whether the entity qualifies for an applicable exemption.

LLCs formed in New York or another U.S. state or territory are currently exempt from NY LLCTA beneficial ownership reporting. However, covered foreign LLCs must comply with the Act unless they qualify for a statutory exemption.

Filing Deadlines

Covered foreign LLCs that were authorized to do business in New York before January 1, 2026, generally have until December 31, 2026 to submit their initial beneficial ownership disclosure or attestation of exemption.

Foreign LLCs authorized to do business in New York on or after January 1, 2026, generally must file within 30 calendar days of registering to do business in New York.

After the initial filing, covered entities are required to submit an annual statement confirming or updating their beneficial ownership information and other required company information.

Filing Fee

A non-refundable $25 filing fee applies to each beneficial ownership disclosure statement and attestation of exemption submitted to the New York Department of State.

Information to Disclose

Each beneficial ownership disclosure must identify every applicable ultimate beneficial owner (UBO), including:

  • Full legal name
  • Date of birth
  • Business or residential address
  • Unique identifying number from an acceptable identification document

UBO Definition

A UBO is generally an individual who:

  • Directly or indirectly owns or controls 25% or more of the LLC; or
  • Exercises substantial control over the entity

If the beneficial owner is a company or other legal entity, the individuals who ultimately own or control that entity may also need to be identified.

Confidential but Enforceable

Beneficial ownership information filed under the NY LLCTA is not publicly available through the state’s records and is exempt from disclosure under New York’s Freedom of Information Law. Access is restricted by law and may be permitted in specified circumstances, including certain government and law-enforcement purposes.

Penalties for Non-Compliance

Failure to comply with the NY LLCTA can result in escalating consequences, including:

  • Past-due status after 30 days
  • Delinquent status after two years
  • Fines of up to USD 500 per day
  • Suspension of the entity’s authority to conduct business in New York
  • Potential action to dissolve or cancel the entity

Why It Matters

The NY LLCTA signals a growing shift toward state-level beneficial ownership transparency in the absence of a uniform federal reporting framework. Companies operating across multiple states or jurisdictions may face increasing compliance complexity as state and federal requirements continue to evolve.

Early preparation can help companies identify applicable filing obligations, maintain accurate beneficial ownership records, document control structures, and coordinate compliance across jurisdictions.

How Can Corpiya Help?

Corpiya’s experts assist clients with:

  • Preparing and submitting NY LLCTA filings
  • Assessing exemption eligibility
  • Identifying and documenting ultimate beneficial owners
  • Developing multi-jurisdictional UBO compliance strategies
  • Coordinating entity compliance requirements across jurisdictions

We help businesses navigate evolving regulatory requirements while maintaining accuracy, confidentiality, and operational efficiency.

Contact us at contact@corpiya.com or fill out the form below to learn more about UBO compliance services.

Related: For help staying ahead of UBO and other annual filing obligations, see Corpiya Counsel’s Corporate Governance & Compliance services.

Disclaimer: This article is provided for general informational purposes only and does not constitute legal advice. Sebastien Gaddini is licensed to practice law in New York; this piece addresses business-expansion and compliance topics in a non-legal, informational capacity and should not be relied upon as legal counsel. For advice specific to your situation, consult a qualified attorney licensed in the relevant jurisdiction.

Put These Insights Into Action

Talk to our team about how this applies to your operations — wherever your business takes you, Corpiya is ready to support your next move.

Get In Touch

Contact - Send us a message

Related Insights

Back to All Insights

Brazil Expansion Playbook: From Market Research to Company Formation

Brazil Expansion Playbook: From Market Research to Company Formation

Brazil is the largest economy in Latin America and one of the most attractive destinations for international expansion. With a population exceeding 215 million, a diversified industrial base, and strong domestic consumption, Brazil offers significant opportunities across sectors such as technology, manufacturing, agribusiness, energy, retail, and financial services.

At the same time, Brazil’s regulatory complexity and tax environment require careful planning and local expertise to ensure a successful market entry. Here is a step-by-step Brazil market entry guide

This guide is part of Corpiya’s broader International Business Expansion Guide — see the full framework for choosing a market and entry model.

1) Conduct Comprehensive Market Research

A successful Brazil market entry strategy begins with a clear understanding of the market, customers, competitors, and regional differences. Brazil is not a uniform market: consumer behavior, purchasing power, infrastructure, and business conditions can vary significantly across states and regions.

Key areas to assess include:

  • Market demand: Evaluate the size of the addressable market, customer needs, purchasing behavior, and expected demand for your products or services.
  • Regional differences: São Paulo, Rio de Janeiro, the South, and the Northeast can present substantially different commercial opportunities, costs, and customer profiles.
  • Consumer and digital trends: Brazil has a large and highly connected consumer base, creating opportunities in e-commerce, digital services, fintech, technology, and mobile commerce.
  • Competitive landscape: Identify established local and international competitors, pricing models, distribution channels, and potential gaps in the market.
  • Market barriers: Assess import requirements, local regulations, taxation, infrastructure, licensing, and other factors that could affect market access.
  • Local partners and channels: Determine whether distributors, agents, strategic partners, or local service providers are necessary to reach customers efficiently.

The objective of Brazil market research is not simply to determine whether demand exists. It is to establish where the opportunity is, who the target customers are, how the market operates, and what resources are required to compete effectively.

2) Choose Your Market Entry Model

Once market demand and competitive conditions have been validated, the next step is determining how your company will establish and operate in Brazil. The appropriate market entry model depends on factors such as investment requirements, regulatory obligations, control over operations, tax considerations, and long-term growth objectives.

Common approaches include:

  • Direct export: Selling products into Brazil through cross-border channels can be appropriate for companies testing demand before establishing a local presence.
  • Distributor or local partner: Working with an established Brazilian company can provide access to local customers, distribution networks, and market knowledge while reducing the initial operational burden.
  • Commercial representation: Local representatives or agents may help develop business relationships and sales opportunities without requiring the same operational footprint as a fully established subsidiary.
  • Brazilian subsidiary or local entity: Companies pursuing long-term operations, hiring employees, signing local contracts, invoicing customers, or establishing a substantial presence may benefit from forming a Brazilian legal entity.
  • Joint venture or strategic partnership: A local partnership can provide market knowledge, relationships, infrastructure, and sector-specific expertise while sharing investment and operational responsibilities.

The right Brazil market entry model should be evaluated alongside company formation, taxation, employment, licensing, foreign investment, and operational requirements. Choosing the wrong structure can create unnecessary costs, compliance obligations, and limitations on future growth.

For companies planning a permanent presence, the decision should therefore be based not only on the fastest way to enter Brazil, but on the structure that provides the best balance of control, compliance, cost, scalability, and long-term commercial objectives.

3) Legal and Regulatory Framework

Brazil’s regulatory environment is complex and requires expert navigation:

  • Company formation: Common structures include the Limitada (Ltda.) and Sociedade Anônima (S.A.).

  • Tax system: Brazil has one of the most complex tax regimes globally, with federal, state, and municipal taxes.

  • Employment laws: Labor regulations are detailed and must be strictly followed to avoid penalties.

4) Cultural and Operational Considerations

  • Language: Portuguese is essential for contracts, operations, and customer engagement.

  • Relationship-driven business culture: Trust and long-term partnerships are highly valued.

  • Operational complexity: Logistics, customs clearance, and compliance vary by state.

5) Marketing and Go‑to‑Market Strategy

  • Localized marketing: Portuguese-language content and Brazil-specific SEO are essential.

  • Digital channels: Social media, marketplaces, and mobile commerce are key growth drivers.

  • Pricing strategy: Must account for taxes, import duties, and regional purchasing power.

6) Manage Risk Proactively

Entering the Brazilian market presents meaningful opportunities, but it also comes with distinct risks that must be actively managed. Regulatory complexity, economic volatility, and operational challenges can affect timelines, costs, and long-term profitability if not addressed early.

A proactive risk management approach—supported by local expertise and strong governance—helps companies protect their investment and maintain operational stability as they scale.

  • Regulatory risk: Frequent tax and regulatory changes require ongoing monitoring and local compliance expertise.

  • Currency volatility: Exchange rate fluctuations can impact pricing, cash flow, and profitability.

  • Operational risk: Strong local partners, clear contracts, and compliance controls are essential to reduce exposure.

Key Brazil Market Data (2020–2024)

The following indicators highlight why Brazil remains a strategic market for foreign investors:

Sources: World Bank, IMF, IBGE

These figures underscore Brazil’s market scale, purchasing power, and long-term growth potential, making it a cornerstone for regional Latin American strategies.

Corpiya Market Entry & Company Formation Services

Entering the Brazilian market successfully requires expert guidance across strategy, legal setup, and compliance. Corpiya supports international companies with end-to-end market entry and company formation services in Brazil, including entity incorporation, tax and regulatory alignment, and operational setup. For the full breakdown of services and country-specific requirements, see our complete guide to expanding your business to Brazil.

By combining local expertise with a structured expansion framework, Corpiya helps businesses reduce complexity, manage risk, and establish a compliant, scalable presence in Brazil—one of Latin America’s most challenging yet rewarding markets.

Positioning Your Business for Success in Brazil

Brazil offers unmatched scale and opportunity in Latin America, but success depends on thorough planning, regulatory compliance, and local execution. Companies that approach market entry with a clear strategy and experienced local support—such as Corpiya’s market entry and company formation services—are best positioned to achieve sustainable growth and long-term success.

If you’re ready to enter the Brazilian market with confidence, reach out to Corpiya at contact@corpiya.com or fill out the form below to start building your roadmap for success.

Disclaimer: This article is provided for general informational purposes only and does not constitute legal advice. Sebastien Gaddini is licensed to practice law in New York; this piece addresses business-expansion and compliance topics in a non-legal, informational capacity and should not be relied upon as legal counsel. For advice specific to your situation, consult a qualified attorney licensed in the relevant jurisdiction.

Put These Insights Into Action

Talk to our team about how this applies to your operations — wherever your business takes you, Corpiya is ready to support your next move.

Get In Touch

Contact - Send us a message

Related Insights

Back to All Insights

Practical Guide to Market Entry in Colombia: Strategies for Success

Practical Guide to Market Entry in Colombia: Strategies for Success

Colombia is one of Latin America’s most dynamic economies, offering significant opportunities for international businesses. With a population of over 51 million and strategic access to both the Pacific and Atlantic markets, Colombia serves as a gateway to the Andean region.

However, entering the Colombian market requires a clear strategy, understanding of local regulations, and cultural adaptation. This practical guide provides actionable steps for companies aiming to expand to Colombia successfully.

This guide is part of Corpiya’s broader International Business Expansion Guide — see the full framework for choosing a market and entry model.

Ready to move from research to execution? See how Corpiya handles company formation, payroll and EOR, and accounting and compliance in Colombia.

1) Conduct Comprehensive Market Research

A successful entry into Colombia begins with understanding the consumer landscape:

  • Digital penetration: ~63% of the population uses the internet, indicating strong potential for digital and e‑commerce strategies. Trade.gov

  • Urban centers: Bogotá, Medellín, and Cali are key commercial hubs with strong logistics and financial ecosystems.

2) Choose Your Market Entry Model

Common approaches include:

  • Exporting: Lower cost; ideal for testing demand.

  • Joint Ventures: Local partner can help navigate regulations and build relationships.

  • Subsidiary / Branch: Best for full operational control.

  • Franchising / Licensing: Effective for retail and service brands.

3) Legal and Regulatory Framework

Foreign companies must comply with Colombian laws:

  • Company setup: The Simplified Joint Stock Company (SAS) is the most flexible and common legal structure.

  • Tax compliance: Understand VAT, corporate tax, and customs duties.

  • Employment law: Ensure compliance with local labor laws and benefits.

4) Understand Cultural and Operational Considerations

Local knowledge is invaluable:

  • Language proficiency: Spanish is essential for customer communication, marketing, and legal procedures.

  • Business culture: Relationship building and trust are critical in negotiations.

  • Payment trends: While digital payments grow, cash and bank transfers remain important.

5) Build A Targeted Go‑to‑Market Strategy

Focus on:

  • Digital marketing & local SEO: Tailor content in Spanish and optimize for Colombia‑specific search intent.

  • Local partnerships: Collaborate with distributors and trade networks.

  • Pricing strategy: Consider purchasing power and regional economic disparities.

6) Manage Risk Proactively

Important risk considerations include:

  • Economic volatility: Monitor exchange rates and GDP trends.

  • Trade balance trends: Colombia shows trade imbalances, which can affect import/export costs.

  • Foreign investment flows: Stay informed on FDI regulations and national sentiment.

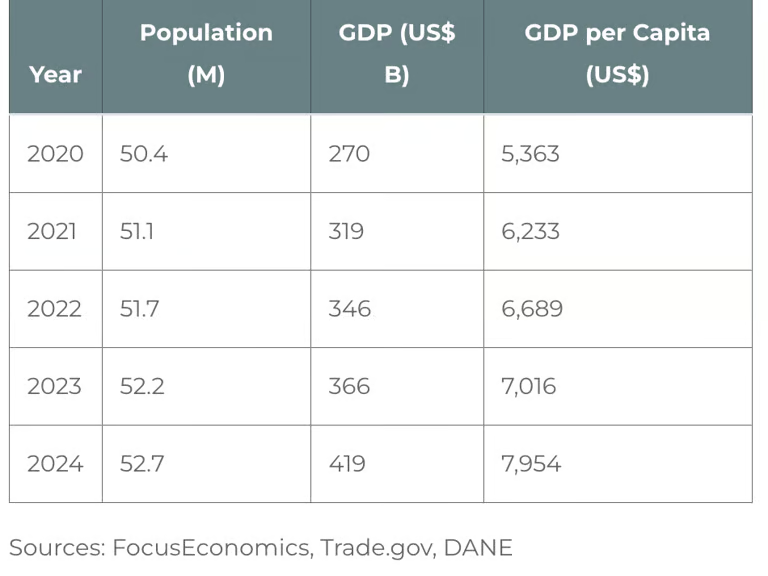
Key Colombia Market Data (2020–2024)

Below is a snapshot of essential economic and demographic indicators to guide market entry decisions:

Corpiya Can Help You Succeed

Successfully entering the Colombian market requires more than strategy—it demands hands-on support from local experts. Corpiya provides comprehensive market entry and company formation services tailored to international businesses.

From registering your Simplified Joint Stock Company (SAS) and navigating taxation, to establishing local operations and compliance, Corpiya helps companies move from planning to execution with confidence. With our insights into the Colombian market and regulatory landscape, your business can accelerate growth, minimize risks, and seize opportunities in Latin America.

Is Colombia Right For Your Business?

With solid economic growth, increasing internet adoption, and an expanding consumer base, Colombia remains an attractive destination for market entry—if supported by strong research, local partnerships, and cultural insight. The data above underscores both the opportunities and pragmatic steps needed to establish a sustainable presence.

If you’re ready to enter the Colombian market with confidence, reach out to Corpiya at contact@corpiya.com or fill out the form below to start building your roadmap for success.

Disclaimer: This article is provided for general informational purposes only and does not constitute legal advice. Sebastien Gaddini is licensed to practice law in New York; this piece addresses business-expansion and compliance topics in a non-legal, informational capacity and should not be relied upon as legal counsel. For advice specific to your situation, consult a qualified attorney licensed in the relevant jurisdiction.

Put These Insights Into Action

Talk to our team about how this applies to your operations — wherever your business takes you, Corpiya is ready to support your next move.

Get In Touch

Contact - Send us a message

Related Insights

Back to All Insights

Entering the U.S. Market: A Guide for Entrepreneurs

Entering the U.S. Market: A Guide for Entrepreneurs

Expanding your business into the United States opens the door to a massive market, stronger investor interest, and increased global credibility. But with these opportunities come complex legal and tax obligations that differ significantly from other jurisdictions, and missing even one requirement can lead to delays, penalties, or disrupted growth plans.

For foreign founders, understanding the U.S. regulatory landscape is essential. From corporate structure and taxes to immigration, employment, and intellectual property, the U.S. market requires careful preparation. This guide outlines the most common pitfalls foreign founders encounter—and how to avoid them to ensure a smooth and compliant expansion.

1. Choose the Right Corporate Structure

Your U.S. entity is the foundation of your expansion. Selecting the wrong structure or state of formation can impact taxation, ownership, and eligibility for investment. Ensure the following is in place:

  • Delaware C-Corporation formation (if seeking venture capital)

  • Foreign qualification in any additional states where you operate

  • Proper issuance of founders’ stock

  • Clear vesting schedules and ownership documentation

2. Understand Federal and State Tax Obligations

The U.S. tax system is multilayered, and foreign founders often overlook state-level taxes or federal filing requirements for foreign-owned companies. Review your obligations in these areas:

  • Federal income tax and withholding rules

  • State franchise taxes, sales taxes, and income tax nexus

  • Permanent establishment risks under tax treaties

  • Annual filings such as Form 1120 and Form 5472

3. Address Immigration and Work Authorization Requirements

Operating in the U.S. without proper authorization can create significant legal risks—founders should plan immigration strategy early. Evaluate the following:

  • Suitable founder-friendly visas (E-2, L-1A, O-1)

  • Activities permitted under ESTA or B-1/B-2 visas

  • Employer I-9 compliance for U.S. hires

  • Immigration timelines relative to fundraising and business launch

4. Protect Intellectual Property in the U.S.

IP rights do not automatically transfer across borders. Protecting your intellectual property early is essential for growth and investment.

  • Register U.S. trademarks for your brand

  • Ensure IP assignment agreements for founders, employees, and contractors

  • Document ownership of software, inventions, and trade secrets

  • Secure patents before public disclosure

5. Manage Cross-Border Ownership and Tax Residency Risks

Where founders live and how ownership is structured can create unexpected tax exposure.

  • Assess U.S. tax residency implications for founders

  • Comply with foreign ownership reporting requirements

  • Manage cross-border income and withholding obligations

  • Avoid double taxation in the U.S. and home country

6. Comply With U.S. Employment Laws

Hiring U.S. workers triggers federal, state, and local obligations, even for a single employee.

  • Classify workers correctly (employee vs. contractor)

  • Use compliant offer letters, agreements, and confidentiality terms

  • Follow state-specific rules on pay, breaks, and termination

  • Maintain workers’ compensation and insurance coverage

7. Maintain Corporate Compliance From Day One

Investors expect clean, accurate records and consistent compliance.

  • File annual reports and pay franchise taxes

  • Keep board resolutions and meeting minutes up to date

  • Maintain a registered agent in every state of operation

  • Document all stock, option, SAFE, and convertible note issuances

8. Meet U.S. Data Privacy and Consumer Protection Standards

Privacy laws vary by state, and GDPR compliance alone is insufficient.

  • Comply with CCPA/CPRA requirements for California consumers

  • Maintain U.S.-specific privacy policies and terms of service

  • Follow rules for data storage and breach notifications

  • Track emerging privacy laws in other states

Key Takeaways

Expanding into the U.S. requires more than forming a company—it demands a strong legal and tax foundation. By addressing these obligations early, foreign founders can minimize risk, avoid delays, and position their company for long-term success in the world’s largest market.

Call to Action

Corpiya Counsel helps foreign founders enter the U.S. market with clarity and confidence. Our subscription-based services provide ongoing guidance to protect your IP, maintain compliance, and avoid costly mistakes.

Contact us at contact@corpiya-counsel.com to build your U.S. expansion on a stronger legal foundation.

Disclaimer: This article is provided for general informational purposes only and does not constitute legal advice. Sebastien Gaddini is licensed to practice law in New York; this piece addresses business-expansion and compliance topics in a non-legal, informational capacity and should not be relied upon as legal counsel. For advice specific to your situation, consult a qualified attorney licensed in the relevant jurisdiction.

Put These Insights Into Action

Talk to our team about how this applies to your operations — wherever your business takes you, Corpiya is ready to support your next move.

Get In Touch

Contact - Send us a message

Related Insights

Back to All Insights

Is Peru Setting the Standard for AI Governance in Latin America?

Is Peru Setting the Standard for AI Governance in Latin America?

Peru is emerging as one of Latin America’s leading jurisdictions for artificial intelligence regulation. With Law No. 31814, which promotes the use of artificial intelligence for the country’s economic and social development, and its implementing Regulation approved through Supreme Decree No. 115-2025-PCM, Peru has established a comprehensive framework for the responsible development and use of AI. The Regulation was approved on September 9, 2025.

For businesses operating in Peru, the framework goes beyond encouraging innovation. It establishes expectations around AI risk classification, transparency, human oversight, protection of fundamental rights, and responsible use of AI systems.

As AI increasingly influences healthcare, finance, education, public services, employment, and business operations, understanding Peru’s AI regulations is becoming an important part of technology governance, regulatory compliance, and risk management.

What Does Peru’s AI Regulation Require?

Peru’s AI framework establishes a risk-based approach to artificial intelligence and seeks to ensure that AI is developed and used safely, ethically, transparently, sustainably, and inclusively while respecting fundamental rights. The Secretariat of Government and Digital Transformation (SGTD) plays a central role in coordinating the country’s AI governance framework and providing technical and regulatory guidance.

For businesses, this means AI governance can no longer be treated solely as an IT or innovation issue. Organizations using AI should consider how systems are selected, documented, monitored, deployed, and overseen throughout their lifecycle.

Peru’s AI Risk Classification: What Businesses Need to Know

The Regulation classifies AI systems and uses according to the risks they may create. This approach is designed to protect fundamental rights while allowing organizations to continue developing and adopting beneficial AI technologies.

Prohibited or Improper Uses

Certain uses of AI are not permitted because of their potential to manipulate individuals, undermine fundamental rights, or create unacceptable risks.

Examples include:

  • AI systems that manipulate or deceive individuals in ways that influence decision-making without adequate awareness
  • Autonomous lethal weapons that operate without human supervision
  • Mass surveillance without an appropriate legal basis or where it disproportionately affects fundamental rights
  • Certain biometric systems used to infer sensitive characteristics or identify individuals in real time in public spaces, subject to specific legal exceptions

These restrictions demonstrate that Peru’s AI framework is focused not only on technological performance but also on protecting individual rights and preventing harmful applications of artificial intelligence.

High-Risk AI Systems

Higher-risk applications require stronger governance, safeguards, and oversight. Areas addressed by the framework include applications involving sectors and decisions where AI can have significant effects on individuals or society.

Examples include:

  • Education and access to educational opportunities
  • Healthcare and other sensitive services
  • Employment and workforce-related decision-making
  • Financial services and credit-related decisions
  • Social programs and public services
  • Critical infrastructure and other sensitive environments

Organizations using higher-risk AI systems should be prepared to address requirements related to transparency, documentation, human oversight, risk management, and accountability.

What Does the Peru AI Act Mean for Businesses?

Companies operating in Peru should treat AI compliance as part of their broader corporate governance and regulatory risk framework.

Key priorities include:

  • AI inventory: Identify the AI systems, tools, vendors, and applications used across the organization.
  • Risk classification: Determine which AI applications may create elevated regulatory, operational, or rights-related risks.
  • Governance policies: Establish clear internal rules governing the acquisition, development, deployment, monitoring, and retirement of AI systems.
  • Human oversight: Define who is responsible for reviewing AI-supported decisions and intervening when necessary.
  • Documentation: Maintain records demonstrating how AI systems are evaluated, implemented, monitored, and governed.
  • Transparency: Establish processes for communicating when and how AI is being used, particularly where individuals may be affected by AI-generated decisions or outputs.
  • Vendor oversight: Evaluate third-party AI providers and incorporate appropriate compliance, security, transparency, and accountability requirements into contracts.
  • Regulatory monitoring: Track changes to Peru’s AI framework and related technical standards as implementation continues.

The framework provides organizations with time to adapt, but companies should not interpret transitional periods as a reason to postpone governance. Building an AI compliance framework early can reduce regulatory risk and create a stronger foundation for responsible AI adoption.

Why AI Governance Can Become a Competitive Advantage in Peru

AI regulation does not have to be viewed solely as a compliance burden. Organizations that establish effective AI governance can use it to strengthen trust with customers, employees, business partners, investors, and regulators.

A structured AI governance program can also help companies:

  • Identify AI-related risks before they become compliance or reputational problems
  • Create consistent standards across business units and jurisdictions
  • Improve accountability for AI-supported decisions
  • Demonstrate responsible technology practices to customers and partners
  • Align local operations with international AI governance principles
  • Build a scalable foundation for future AI adoption

For multinational companies, Peru’s framework is particularly relevant because AI governance increasingly intersects with data protection, cybersecurity, employment, consumer protection, corporate governance, and cross-border compliance.

What Should Companies Do Now?

Organizations using or planning to deploy AI in Peru should begin by establishing a clear understanding of their current AI footprint.

A practical starting point includes:

  1. Identify AI use cases across departments, subsidiaries, and business functions.
  2. Map AI vendors and systems and determine what data and decisions each system affects.
  3. Classify potential risks based on the purpose and impact of each AI application.
  4. Document governance responsibilities so ownership of AI compliance is clearly established.
  5. Review contracts and vendor controls for transparency, data protection, security, and accountability requirements.
  6. Establish monitoring and review processes for higher-risk AI systems.
  7. Track regulatory developments as Peru continues implementing and refining its AI governance framework.

Taking these steps early can help businesses move from reactive compliance to proactive AI governance.

How Corpiya Helps Companies Navigate Peru’s AI Framework

Corpiya supports organizations entering or operating in Peru by helping them understand and operationalize emerging AI governance requirements.

Our support can include:

  • Assessing AI risk classifications and applicable obligations
  • Developing internal AI governance and compliance policies
  • Establishing documentation and oversight processes
  • Supporting impact and risk assessments for higher-risk AI systems
  • Reviewing third-party AI and technology arrangements
  • Coordinating compliance requirements across multiple entities and jurisdictions
  • Monitoring regulatory developments affecting AI and corporate operations

Navigating Peru’s AI framework can involve complex compliance requirements, documentation, and coordination across business units and legal entities. Corpiya combines regulatory and operational expertise with technology-enabled entity management to help organizations maintain visibility over their corporate structures, obligations, documentation, and compliance deadlines.

Corpiya’s AI-driven Entity Management System centralizes entity data, automates workflows, tracks deadlines, and supports ongoing compliance management across jurisdictions. This integrated approach helps organizations establish stronger governance infrastructure while continuing to pursue responsible AI adoption.

The Future of AI Governance in Latin America

Peru’s AI framework represents an important development in the region’s approach to artificial intelligence regulation. By establishing rules around responsible AI use, risk, transparency, and protection of fundamental rights, Peru is helping shape the direction of AI governance in Latin America.

For companies operating in Peru, the priority is no longer simply understanding what AI can do. It is understanding how AI should be governed, documented, monitored, and deployed responsibly.

Organizations that build AI governance into their operating model now will be better positioned to manage regulatory change, protect stakeholder trust, and scale AI responsibly as the regulatory landscape continues to evolve.

For more information or tailored support, including how our AI-driven Entity Management System can streamline compliance and entity governance, fill out the form below or contact us at contact@corpiya.com.

Disclaimer: This article is provided for general informational purposes only and does not constitute legal advice. Sebastien Gaddini is licensed to practice law in New York; this piece addresses business-expansion and compliance topics in a non-legal, informational capacity and should not be relied upon as legal counsel. For advice specific to your situation, consult a qualified attorney licensed in the relevant jurisdiction.

Put These Insights Into Action

Talk to our team about how this applies to your operations — wherever your business takes you, Corpiya is ready to support your next move.

Get In Touch

Contact - Send us a message

Related Insights

Back to All Insights